|
China's tilapia export destinations reshuffled! The United States drops to third place by export volume.Time:2026-11-06
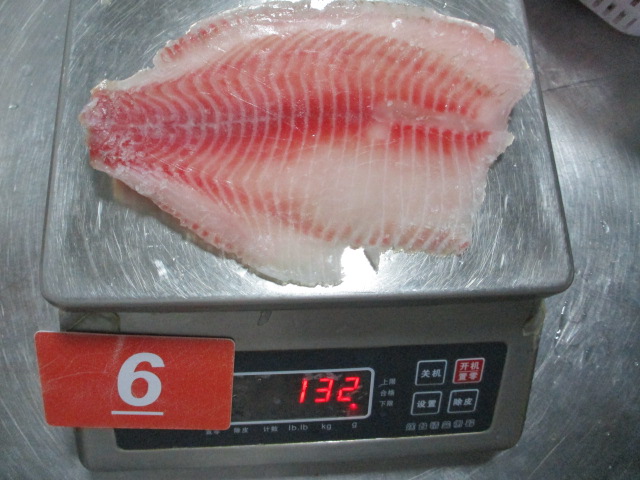
Frozen tilapia fillets3-5oz, 100%nw, China origin, skinless, boneless, IQF/IVP Welcome to contact us for tilapia fillets orders: sales@blueseafishery.cn Blue Sea Fishery Co., Ltd. wechat: DORIS85789 E-mail: sales@blueseafishery.cn China tilapia fillets supplier, gutted and scaled tilapia supplier/producer Week 45 of 2026 (November 2–8): Raw tilapia delivered prices at processing plants in major southern production regions of China diverged. For the 500–800g size, prices rose by RMB 0.20 per kilogram in Hainan, while dropping by RMB 0.10 per kilogram in Guangdong and Guangxi for the same specification. The price gap between Hainan and Guangdong-Guangxi narrowed, marking a clear divergence in raw material price trends across southern producing areas. This week, Hainan’s delivered plant price increased by approximately USD 0.03 per kg, whereas procurement prices at processing plants in Guangdong and Guangxi edged down slightly. Regional price movements were not uniform, and quotations for 500–800g raw fish represented the key market shift in southern producing areas this week. For processors, regional disparities in raw material procurement costs have narrowed, though purchase prices still vary across production zones. Côte d’Ivoire and Mexico Surpass the United States; Export Market Landscape ShiftsChanges in China’s tilapia export markets have been particularly notable. At the 2026 China Seafood Summit, the Hainan Aquatic Products Processing and Marketing Association revealed that by export volume, the United States has fallen from China’s top tilapia export destination to third place, with Côte d’Ivoire and Mexico ranking first and second respectively. From January to August 2026, China exported 106,100 tonnes of tilapia products to Côte d’Ivoire, 68,200 tonnes to Mexico, and 61,600 tonnes to the United States. U.S.-bound export volume declined by 13.2% year-on-year, widening the volume gap compared with shipments to Côte d’Ivoire. Nevertheless, the United States remains China’s most valuable tilapia market by export value. This is largely due to differing product mixes: China’s exports to the U.S. are dominated by higher value-added products such as fillets, while African buyers mostly purchase whole frozen fish. Differences in unit product value mean the U.S. retains the top spot in export revenue even as it slips to third by volume. Between January and August 2026, China’s tilapia export value to the U.S. stood at roughly USD 150 million, down 36% year-on-year. While export volume fell 13.2%, the steeper 36% drop in export value indicates China’s U.S.-bound shipments are pressured not only by lower volumes but also weaker product values. U.S. Imports Fall in Both Volume and Value; China Remains at a Tariff DisadvantageU.S. import data confirms shrinking purchasing activity. In August 2026, U.S. tilapia imports totalled 7,086 tonnes, down 33.1% year-on-year, with an import value of USD 22.25 million, a 40.5% year-on-year decline. The larger fall in value versus volume points to a drop in the average value of imported tilapia that month. Tariff differentials remain a critical competitive challenge for Chinese exporters. Under the referenced tariff schedule, Chinese tilapia shipped to the U.S. attracts a 37.5% tariff, compared with around 10%–12.5% for shipments from Indonesia and Vietnam. Chinese products carry a heavier import tax burden in the U.S. market, giving Indonesian and Vietnamese suppliers a distinct tariff advantage. In its October 2026 tilapia market analysis, the Food and Agriculture Organization of the United Nations (FAO) identified weak U.S. demand and shifting trade flows as key features of the global tilapia market in 2026. The agency previously reported that China’s frozen whole tilapia exports rose 39.4% year-on-year in Q1 2026, including 38,900 tonnes to Côte d’Ivoire. Over the same period, China’s exports to the United States dropped 34.5%. Rising African purchases of Chinese whole frozen tilapia contrast with contracting U.S. imports.
U.S. Wholesale Quotations Stable in Week 44; Restocking Acceptance Yet to Be SeenU.S. wholesale prices for frozen tilapia held steady across the established quotation range in Week 44 (October 26–November 1). Ample inventories and cautious buying sentiment among U.S. buyers have temporarily offset the impact of shifting Chinese raw material prices and restocking offers. The lack of a corresponding rise in U.S. wholesale prices alongside Chinese raw material quotations shows that importer stock levels continue to dictate purchasing timelines. For Chinese exporters, whether buyers in the U.S. will accept new offers depends not only on raw material costs but also on how quickly importers draw down existing inventory and their actual restocking needs. Prices diverged across southern China in Week 45, with Hainan posting gains and Guangdong-Guangxi seeing falls. The U.S. market, meanwhile, remains characterised by stable wholesale prices and cautious buying. Market attention will now focus on U.S. inventory turnover and importers’ willingness to accept higher restocking quotations.
|